OG CANNABIS INSURANCE.COM

SO. CAL’S BEST INSURANCE SERVICES, INC.

9587 Arrow Rte. Suite K
Rancho Cucamonga, CA 91730

(877) 473-7979

GET A QUOTE

Available in All Legalized States

CBD and Hemp Insurance Now Available
OG Cannabis Insurance Blog

The insurance game is an ever-changing environment, especially in the Cannabis Dispensary Insurance sector. There are a variety of different factors (e.g. cannabis laws and policies) that can affect the way your insurance works and how you and your business are covered.

The OG Cannabis Insurance blog keeps you up to date on cannabis insurance, laws and policies, and dispensary insurance news so you can be proactive on protecting yourself when the unexpected happens. We update our cannabis insurance blog regularly so check back soon for more posts!

Minnesota Cannabis Business Insurance & OCM Compliance Guide: Requirements, Chapter 342 Mandates, and Cost Breakdown

Minnesota Cannabis Business Insurance & OCM Compliance Guide: Requirements, Chapter 342 Mandates, and Cost Breakdown

By Manuel Cuaron, OG Cannabis Insurance

Minnesota cannabis business insurance requires a deep understanding of state regulations and compliance mandates. The cannabis industry, with its unique challenges and risks, necessitates tailored insurance solutions that not only protect business operations but also ensure compliance with the Minnesota Office of Cannabis Management (OCM). This guide offers insights into the essential insurance requirements mandated by Chapter 342, the impact of OCM compliance on insurance policies, and the overall cost breakdown for cannabis businesses in the state. Business owners will learn how to optimize their insurance strategies while fulfilling regulatory obligations. The following sections will cover key aspects such as mandatory insurance requirements, the implications of OCM compliance, and specialized insurance options available to operators.

What Are the Minnesota Cannabis Insurance Requirements for Business Owners?

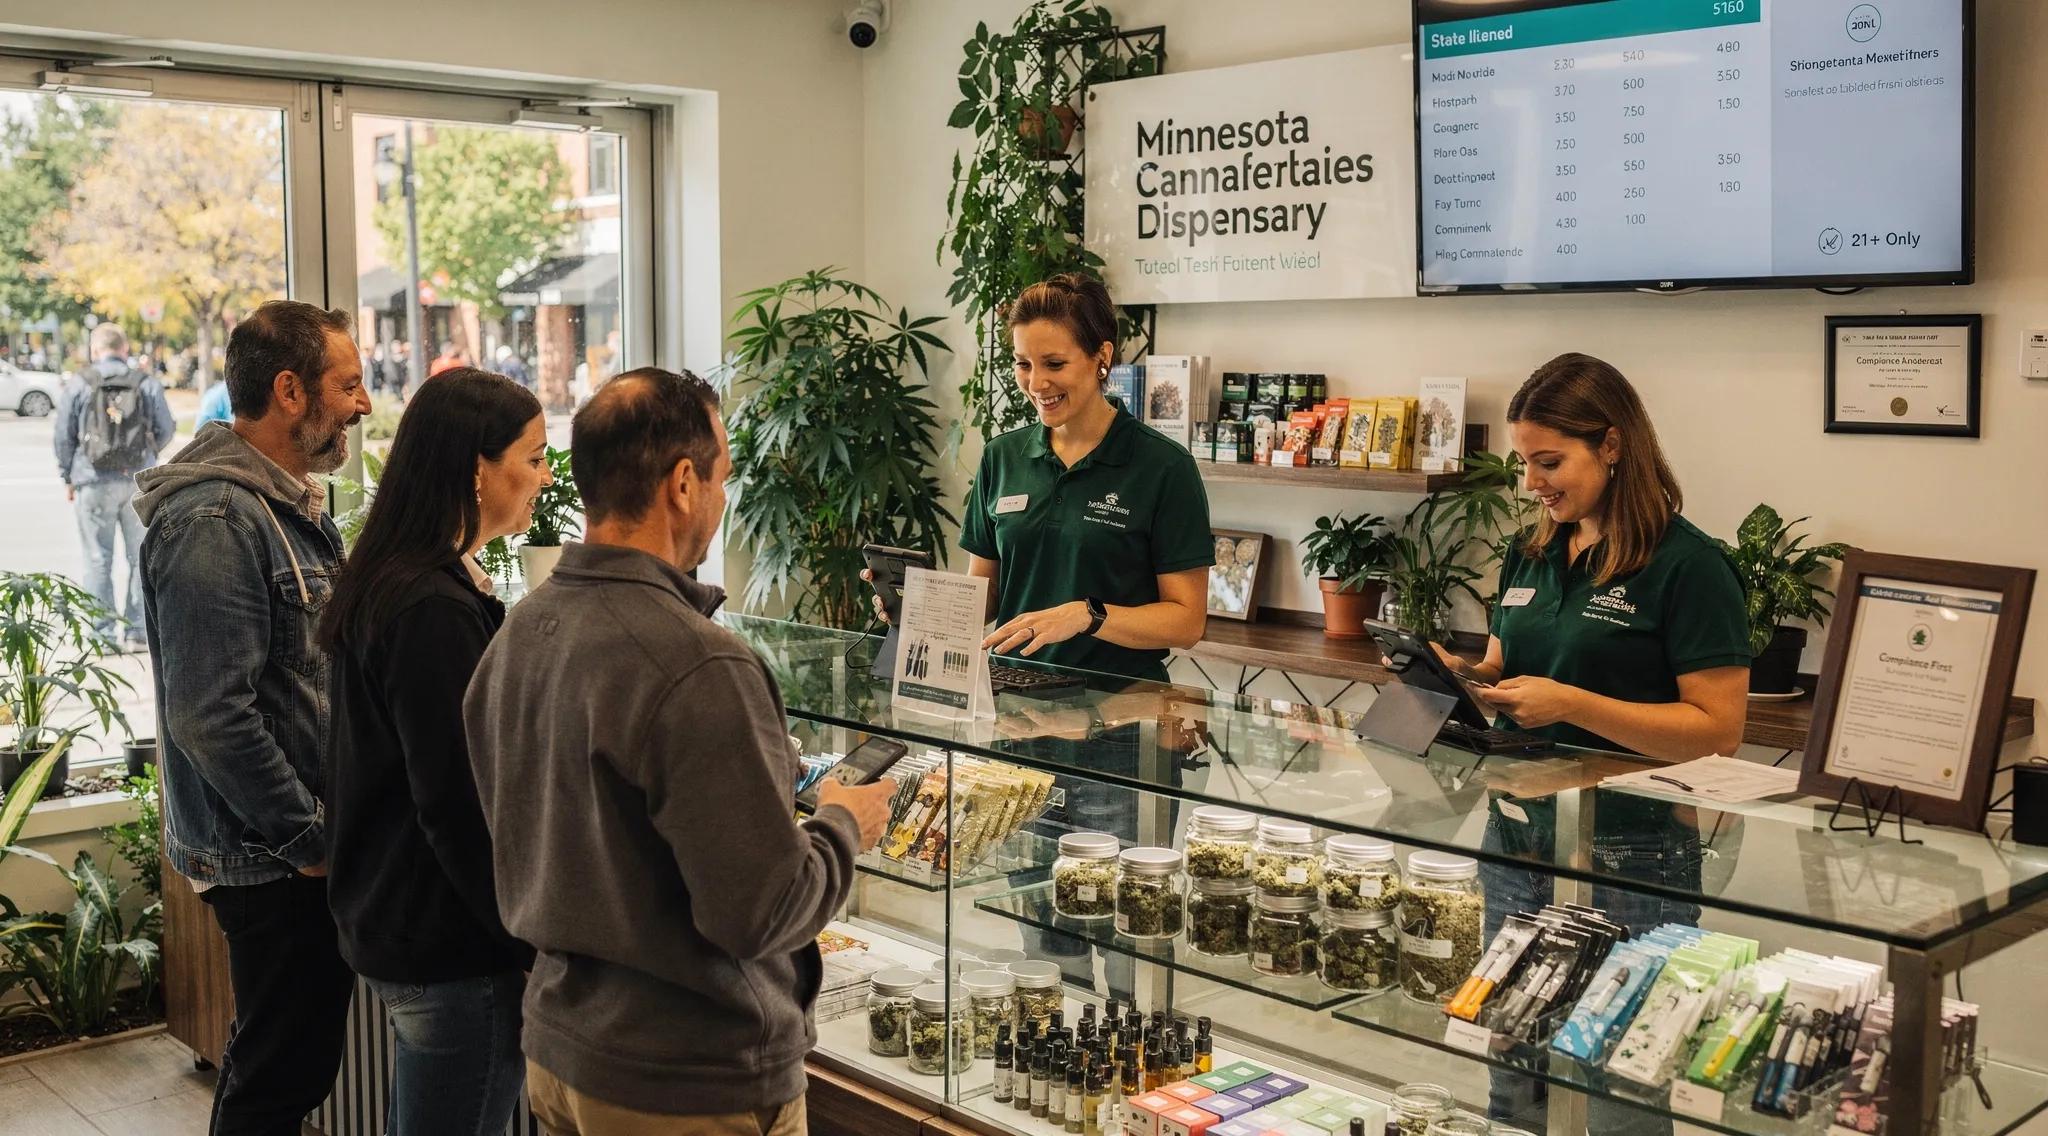
Insurance broker advising cannabis business owner on insurance requirements

Minnesota cannabis business owners must adhere to specific insurance requirements to maintain compliance and protect their operations. The fundamental insurance coverages mandated include General Liability Insurance and Workers’ Compensation Insurance. General Liability Insurance is designed to protect against claims involving bodily injury or property damage that may arise during business operations. Cannabis workers compensation insurance is essential for covering medical expenses related to employee injuries incurred while on the job.

In addition to these requirements, cannabis businesses may consider additional coverages to ensure comprehensive protection against various risks inherent in the industry. So. Cals Best Insurance Services, Inc specializes in delivering insurance solutions tailored for cannabis businesses, ensuring alignment with Minnesota’s compliance needs.

Which Coverage Types Does Chapter 342 Mandate for Cannabis Businesses?

Chapter 342 insurance requirements outline the critical coverage types that cannabis businesses must secure to operate legally within Minnesota. Mandated coverages include:

  1. General Liability Insurance: Required to protect against claims of bodily injury or property damage that may occur during the course of business operations.
  2. Workers’ Compensation Insurance: Mandatory for all employees, ensuring that medical expenses due to work-related injuries are covered.
  3. Surety Bond: Depending on the nature of the operation, this may be required for license applicants to comply with regulatory requirements.

Familiarity with these mandated coverages is crucial for maintaining compliance and safeguarding the business against potential liabilities.

How Does OCM Compliance Impact Minnesota Cannabis Insurance Policies?

OCM compliance significantly influences how Minnesota cannabis businesses approach their insurance policies. Compliance with state laws often leads to increased insurance premiums, as operators may be required to obtain specialized insurance that addresses the unique risks associated with the cannabis industry. Understanding the implications of compliance can help business owners negotiate better terms with insurers, ensuring they get the coverage necessary without overextending their budgets.

Additionally, having adequate insurance coverage reduces financial risks that may emerge from operational liabilities, enhancing the company’s appeal to investors and partners. Ensuring compliance is not just about legal requirements; it’s also about establishing credibility in a competitive market.

How Is Cannabis Business Insurance Coverage Structured Under Minnesota Law?

Understanding the structure of cannabis business insurance coverage is critical for operators to ensure they meet state mandates and protect their interests. Minnesota law outlines specific coverage types that businesses must secure, emphasizing the importance of compliance with evolving regulations. Documentation and regular audits play a vital role in this process, helping businesses maintain accurate records of their insurance policies.

The mandatory insurance types, including General Liability and Workers’ Compensation, must be properly documented and reassessed regularly to account for any changes in business operations or the regulatory landscape.

What Liability and Product Liability Policies Are Essential?

Liability coverage is crucial for cannabis businesses, particularly to protect against third-party claims of bodily injury or property damage. This is especially important in an industry where product safety is a critical concern.

  1. Cannabis General Liability Insurance (Minnesota): Offers protection against general claims, including bodily injury and property damage.
  2. Cannabis Product Liability Insurance: Ensures that manufacturers and distributors are protected against claims related to product defects and safety issues.

These policies not only shield businesses from potential lawsuits but also enhance consumer trust and credibility in a highly scrutinized industry.

Which Specialized Insurance Options Should Cannabis Operators Consider?

In addition to mandatory coverages, cannabis operators in Minnesota should explore several specialized insurance options that can further protect their businesses:

  • Product Liability Insurance: Essential for ensuring consumer safety and compliance, particularly for dispensaries selling consumables.
  • Crop Insurance: Important for cultivators, offering protection against crop loss due to unforeseen circumstances such as natural disasters or pests.
  • Cyber & Theft Insurance: As cannabis businesses often carry significant cash and valuable inventory, protection against data breaches and theft is critical.

These specialized insurance products enable cannabis operators to mitigate specific risks while ensuring thorough protection for their operations.

What Are Typical Minnesota Cannabis Liability Insurance Costs?

Minnesota cannabis insurance cost varies widely based on the type of business and its specific risk profile. Generally, dispensaries can expect to pay between $1,500 to $3,000 or more annually for liability insurance, while cultivators may incur costs ranging from $1,500 to $4,000 annually.

These costs are influenced by several factors, including location, claims history, and the types of coverage selected. Understanding typical costs can help cannabis businesses budget effectively and ensure adequate protection without compromising their financial stability.

Which Factors Influence Insurance Premiums for Cannabis Businesses in Minnesota?

Several key factors influence the insurance premiums for cannabis businesses in Minnesota:

  1. Type of Business: Different types of operations (cultivators vs. dispensaries) incur varying levels of risk, which can directly affect premium rates.
  2. Geographic Location: Businesses in urban areas may face higher premium charges due to increased risks associated with theft or liability claims.
  3. Security Measures: Implementing thorough security protocols can positively affect premium rates, as insurers may discount premiums for businesses that demonstrate proactive risk management.

Managing these factors effectively can lead to more favorable insurance terms and lower overall costs.

How Can Business Owners Optimize Insurance Costs While Maintaining Compliance?

To optimize insurance costs while ensuring compliance, cannabis business owners can take several strategic steps:

  1. Request Quotes: By obtaining quotes from multiple providers, businesses can compare pricing and coverage options to find the best fit for their needs.
  2. Conduct Regular Safety Audits: Regular assessments can help businesses identify potential risks and address them proactively, potentially leading to lower premiums.
  3. Stay Informed on Regulatory Changes: Keeping abreast of changes in laws and regulations will help ensure ongoing compliance and guide necessary adjustments to insurance coverage.

By implementing these strategies, cannabis business owners can effectively manage their insurance expenses while maintaining a compliant and secure operation.

How Can Cannabis Startups Ensure OCM Compliance Through Insurance?

Cannabis business owner auditing compliance documentation and insurance papers

For cannabis startups, ensuring OCM compliance through insurance involves several critical steps:

  1. Understand Minimum Coverage Requirements: It is essential for startups to clearly understand the insurance coverage and limits required for OCM compliance.
  2. Work with Specialized Brokers: Engaging brokers who specialize in cannabis insurance can provide tailored guidance to help meet compliance needs effectively.
  3. Regularly Audit Compliance Status: Conducting frequent reviews of compliance status and insurance coverage helps identify any gaps that may need addressing.

These measures can help new cannabis businesses establish themselves on solid legal footing, drawing on the expertise of insurance professionals to navigate the complexities of compliance.

What Steps Are Required to Secure Insurance that Meets OCM Standards?

Securing insurance that meets OCM standards involves a systematic approach:

  1. Gather Necessary Documentation: Compile all relevant records, including business licenses, operation details, and prior insurance history, for insurance applications.
  2. Request Coverage Quotes: Evaluate offers from various providers to compare coverage options and pricing effectively.
  3. Conduct Regular Compliance Audits: Regularly reviewing compliance with OCM regulations ensures ongoing adherence and can guide necessary adjustments to coverage.

By following this procedure, businesses can ensure they are adequately protected while fulfilling their regulatory responsibilities.

How Does OCM Compliance Insurance Protect Cannabis Entrepreneurs and Investors?

OCM compliance insurance plays a critical role in protecting cannabis entrepreneurs and investors in several significant ways:

  1. Legal Protection: It provides essential coverage that helps cannabis businesses operate within legal frameworks, minimizing the risk of penalties and legal challenges.
  2. Financial Risk Mitigation: Adequate insurance coverage reduces the potential financial risks associated with operational liabilities, safeguarding business assets and investments.
  3. Maintained Credibility: Insurance compliance enhances business credibility in the eyes of consumers and investors, fostering trust and a positive reputation in a competitive market.

By understanding these protections, cannabis entrepreneurs can appreciate the value of comprehensive insurance in their overall business strategy.

Coverage TypeDescriptionRequirements
General Liability InsuranceProtects against claims of bodily injury and property damageRequired for all cannabis businesses
Workers’ Compensation InsuranceCovers medical expenses for injured employeesMandatory for employers in Minnesota
Surety BondEnsures compliance with regulations for license applicantsMay be required based on business type

This table summarizes essential coverage types necessary for compliance under Minnesota cannabis regulations, highlighting the critical nature of each coverage for successful business operations.

Influencing FactorExplanationImpact on Premiums
Type of BusinessDifferent operations carry varying risksHigher risk may elevate premiums
Geographic LocationUrban businesses may face increased theft riskLocation can lead to variable costs
Security MeasuresEnhanced protection may lower premiumsProactive measures can result in discounts

This comparison illustrates how various factors can influence insurance premium costs for cannabis businesses, emphasizing the importance of strategic planning to optimize expenses.

Cannabis businesses in Minnesota face unique challenges due to the interplay of complex regulations and the inherent risks of the industry. By understanding and implementing the necessary insurance requirements while ensuring adequate compliance, business owners can mitigate risks, enhance their reputation, and maintain a competitive edge in a rapidly evolving market.

Frequently Asked Questions

What insurance is legally required for cannabis businesses in Minnesota?

Under Chapter 342 insurance requirements, Minnesota cannabis businesses must carry General Liability Insurance and Workers’ Compensation Insurance. Depending on the license type, a Surety Bond may also be required. Together, these coverages protect against bodily injury and property damage claims, cover employee medical expenses from work-related injuries, and satisfy state licensing conditions.

How much does Minnesota cannabis business insurance typically cost?

Minnesota cannabis insurance cost varies by operation type. Dispensaries generally pay between $1,500 and $3,000 or more annually for liability coverage, while cultivators can expect costs ranging from $1,500 to $4,000 annually. Actual premiums depend on location, claims history, and the specific coverages selected.

Does OCM compliance affect my insurance premiums?

Yes. OCM compliance often requires specialized coverage tailored to cannabis-specific risks, which can influence premium levels. Maintaining strong compliance records and adequate coverage can help business owners negotiate better terms with insurers while reducing overall financial risk.

What’s the difference between general liability and product liability insurance for cannabis businesses?

Cannabis general liability insurance in Minnesota covers third-party claims of bodily injury or property damage arising from business operations. Cannabis product liability insurance specifically protects manufacturers and distributors against claims tied to product defects or safety issues, which is especially important for businesses selling consumables.

What steps should cannabis startups take to meet OCM insurance standards?

Cannabis startups should first understand the minimum coverage requirements for OCM compliance, then work with brokers who specialize in cannabis insurance to secure appropriate policies. Gathering documentation such as business licenses and prior insurance history, requesting quotes from multiple providers, and conducting regular compliance audits all help ensure coverage stays aligned with OCM standards over time.

Ready to Protect Your Minnesota Cannabis Business?

Navigating Chapter 342 requirements and OCM compliance is easier with the right insurance partner. Get a Quote today to secure tailored coverage that keeps the business compliant and protected.

Get a Personalized Cannabis Insurance Quote

Before reviewing the requirements below, Minnesota cannabis operators can move quickly by requesting a personalized quote. Get a Quote to start building a compliant, cost-effective insurance program tailored to the business.

Copyright © OG Cannabis Insurance. All Rights Reserved.

img Click To Call!