OG CANNABIS INSURANCE.COM

SO. CAL’S BEST INSURANCE SERVICES, INC.

9587 Arrow Rte. Suite K
Rancho Cucamonga, CA 91730

(877) 473-7979

GET A QUOTE

Available in All Legalized States

CBD and Hemp Insurance Now Available
OG Cannabis Insurance Blog

The insurance game is an ever-changing environment, especially in the Cannabis Dispensary Insurance sector. There are a variety of different factors (e.g. cannabis laws and policies) that can affect the way your insurance works and how you and your business are covered.

The OG Cannabis Insurance blog keeps you up to date on cannabis insurance, laws and policies, and dispensary insurance news so you can be proactive on protecting yourself when the unexpected happens. We update our cannabis insurance blog regularly so check back soon for more posts!

California Cannabis Insurance & DCC Compliance Guide: Surety Bond Requirements, Insurance Coverage, and Cost Breakdown

California Cannabis Insurance & DCC Compliance Guide: Surety Bond Requirements, Insurance Coverage, and Cost Breakdown

By Manuel Cuaron, OG Cannabis Insurance

California cannabis insurance and the requirements set forth by the Department of Cannabis Control (DCC) form a complex landscape for many in the industry. This guide addresses DCC compliance for cannabis businesses in detail, covering DCC surety bond requirements, the insurance coverage types necessary for cannabis operations, and a full California cannabis business insurance cost breakdown for prospective business owners. As the cannabis industry continues to evolve, understanding these obligations and protective measures is crucial. This article details the requirements for securing a cannabis surety bond in California, the various types of insurance coverage available, and provides a comprehensive cost analysis, so you are well-informed and prepared to succeed in California’s regulatory landscape.

Get a Quote for Your Cannabis Insurance

Securing the right surety bond and insurance coverage is essential for California cannabis businesses working to maintain DCC compliance. OG Cannabis Insurance helps operators navigate these requirements with tailored coverage solutions — get a quote to start protecting your business today.

Surety Bond Requirements

A surety bond is a crucial component for cannabis businesses, required to ensure compliance with state regulations and foster trust among consumers and authorities. In California, the DCC mandates specific bond amounts to secure licenses before businesses can operate legally. The bond functions as a financial guarantee that contract obligations, including compliance with statutory requirements, will be fulfilled. Breaking down these requirements helps prospective cannabis operators prepare adequately to meet state standards.

Bond Amounts

Understanding the bond amounts is essential for cannabis operations. The standard bond amount required is $5,000 per license, ensuring that operators meet the basic financial threshold necessary to maintain compliance. However, certain municipalities impose higher bond requirements; for instance, in Coalinga, the required bond amount can be as high as $25,000, reflecting local regulations. Meanwhile, cities like Los Angeles adhere to the standard of $5,000 per license. These variations highlight the importance of local jurisdiction awareness for businesses planning to operate in multiple areas.

Application Process

Securing a surety bond involves a systematic application process. Potential applicants must prepare to submit relevant documentation, demonstrating their business’s financial stability. Typically, the steps to apply include providing business plans and financial statements, including credit information, as underwriting may vary based on the applicant’s credit history. Most bonds are issued in a swift time frame, typically within 1 to 2 business days, allowing businesses to commence operations more swiftly than traditional financing methods.

Types of Insurance Coverage Available

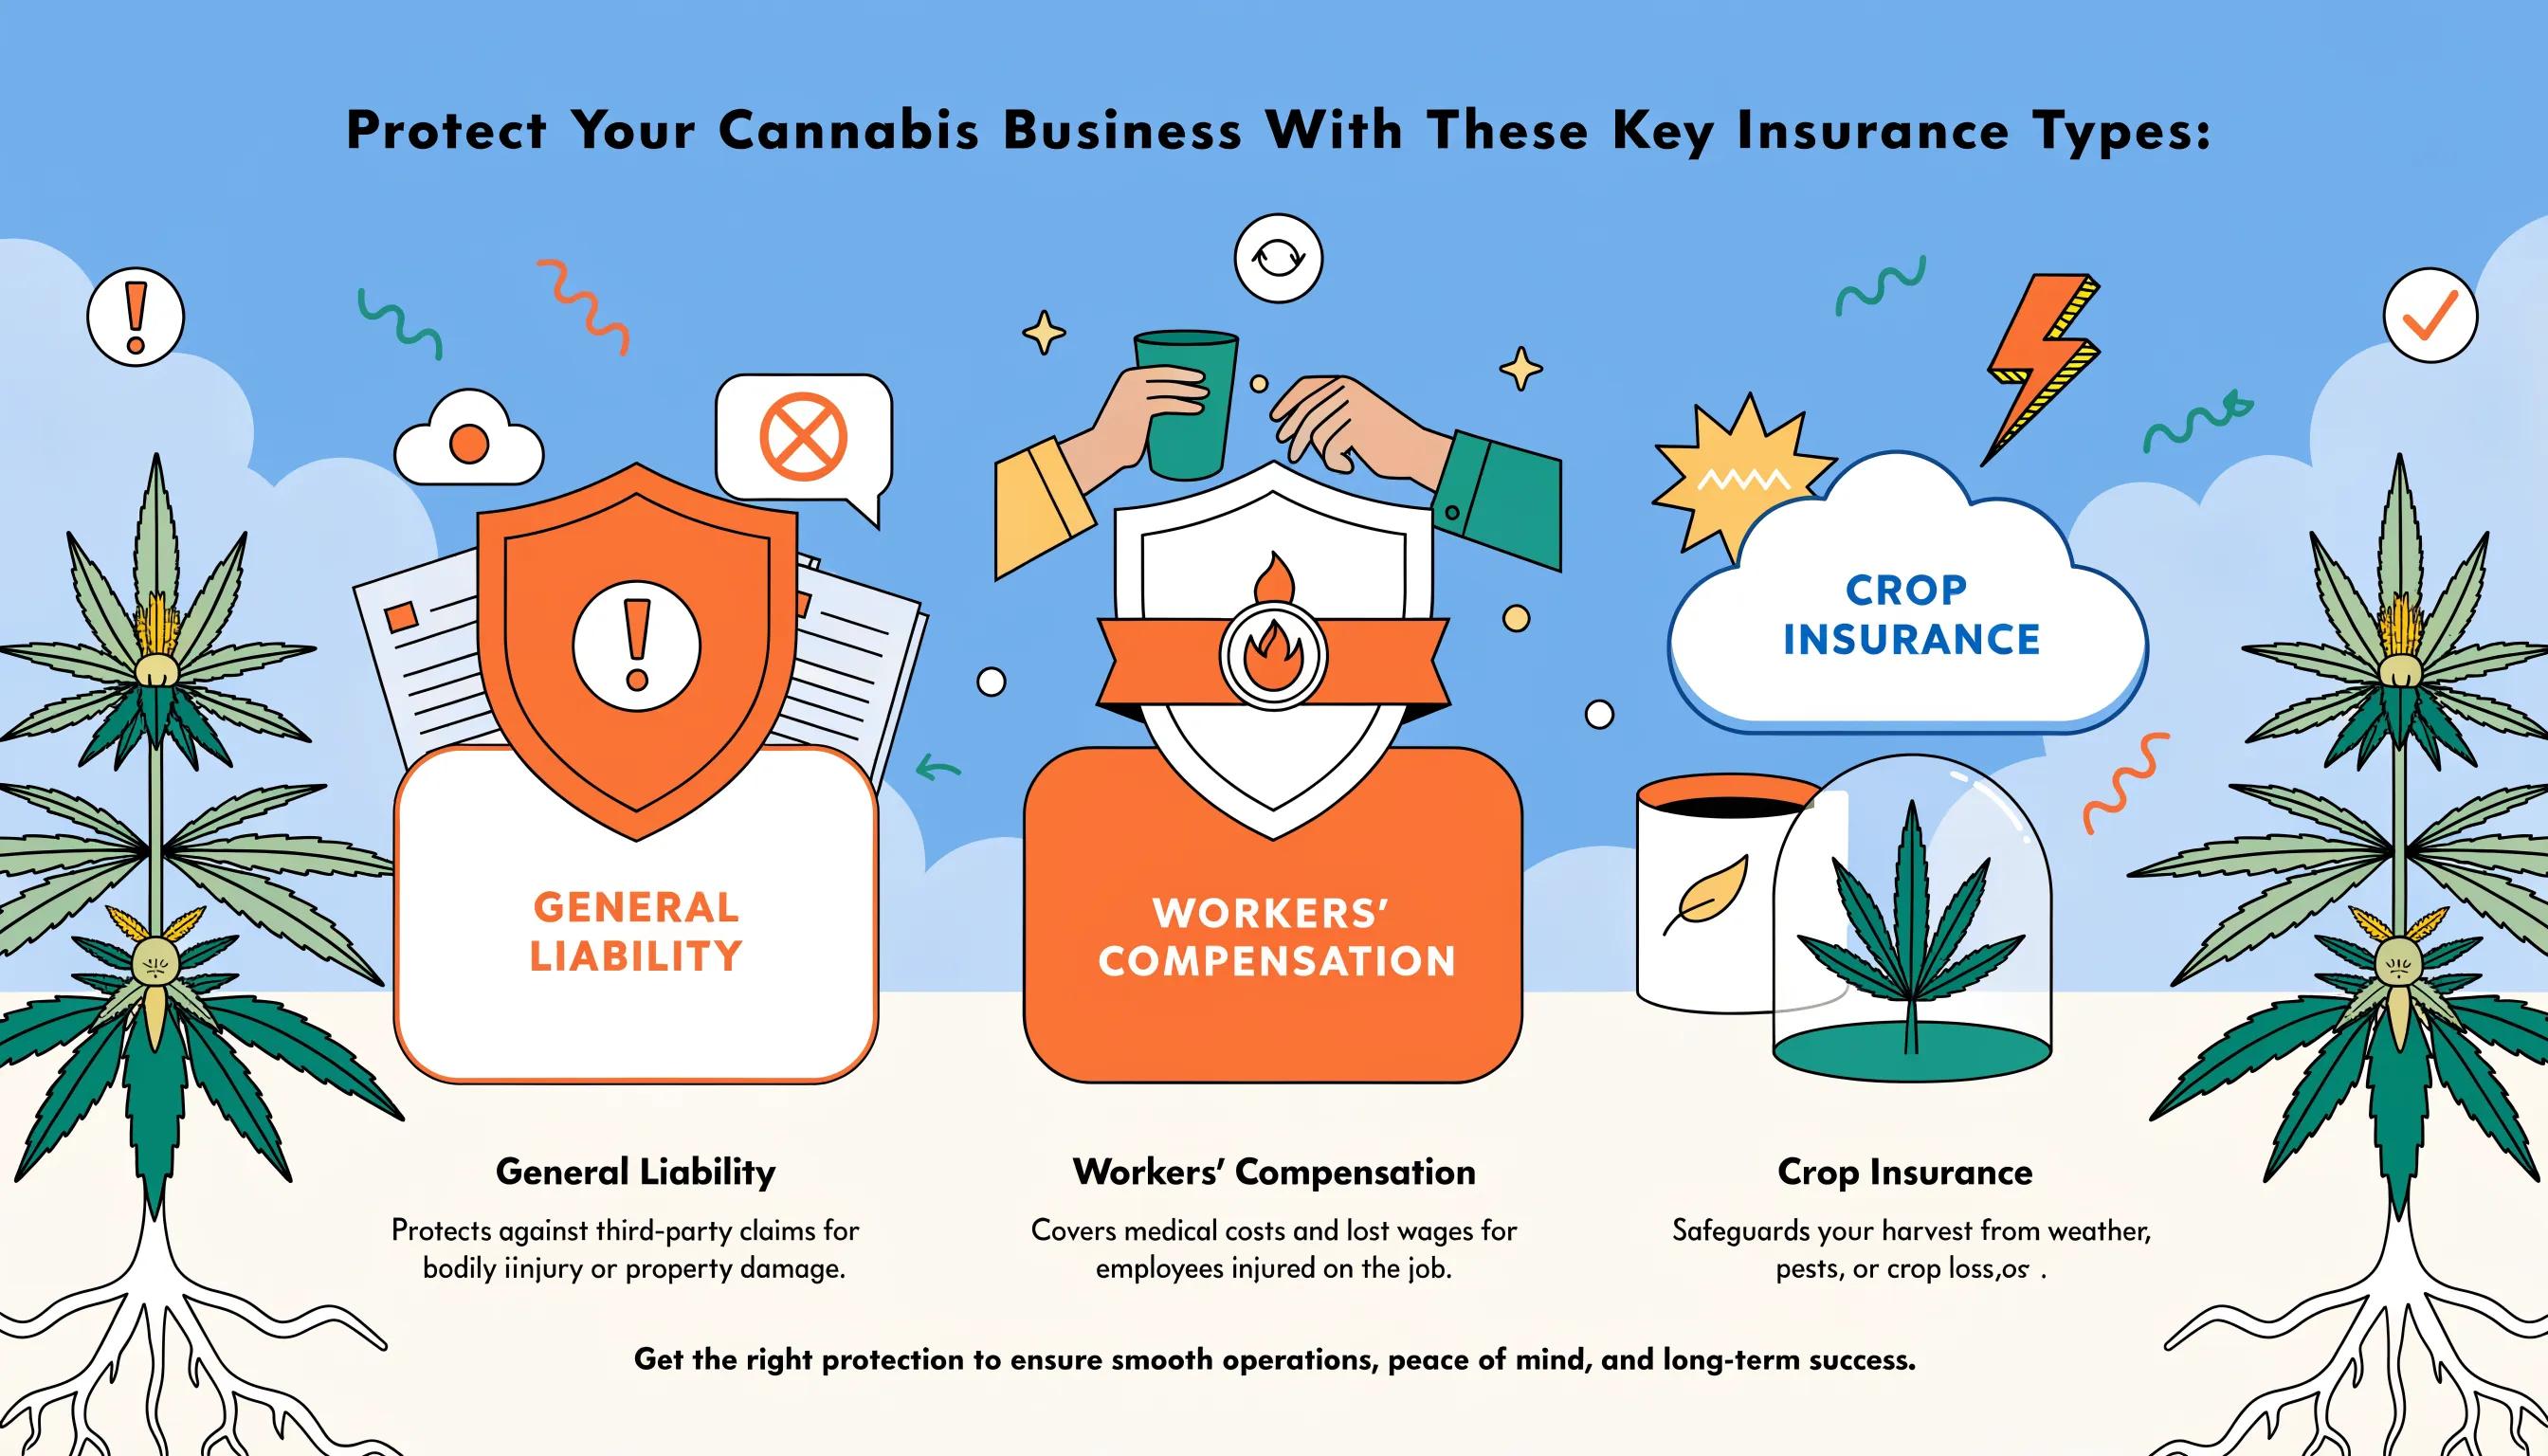
Cannabis insurance coverage types: general liability, workers' compensation, crop insurance

In the cannabis industry, specific insurance policies are essential to safeguard businesses against potential risks and liabilities. Many cannabis operations are required to carry certain coverages, while others may be highly recommended to ensure comprehensive protection. Familiarizing oneself with the types of coverage available can significantly mitigate financial exposures associated with operating in a regulated sector.

  • Cannabis General Liability Insurance (California): This is crucial for protecting businesses against claims of bodily injury or property damage. Most cannabis businesses must have a minimum coverage of $1,000,000 per occurrence, with aggregate limits often reaching $2,000,000.
  • Workers’ Compensation Insurance: As mandated by California law, any business with employees must have workers’ compensation insurance to cover medical expenses and compensation for work-related injuries.
  • Crop Insurance: While not universally required, crop insurance protects against loss of income due to factors like natural disasters, disease, or pests, ensuring financial stability.

As cannabis businesses increasingly seek tailored insurance products, providers like So. Cals Best Insurance Services, Inc. offer specialized services designed to address these industry-specific needs, ensuring comprehensive coverage solutions for unique challenges faced by cannabis enterprises.

Regulatory shifts across the state highlight how mandatory coverage frameworks continue to shape the operational environment for legal operators.

California Cannabis Insurance Mandates and Market Evolution California’s Department of Insurance now requires that carriers serving California insureds provide coverage for the cannabis industry, and will require the evolution of the cannabis industry at a rapid pace. Risk management within the cannabis industry: Building a framework for the cannabis industry, 2019

Cost Breakdown

Cannabis insurance cost breakdown by license type: cultivators, dispensaries

Cannabis insurance costs can vary widely based on a host of factors, including the type of coverage, the size of the operation, and the specific risks involved. Understanding the components that influence these costs can help business owners budget accordingly and secure appropriate policies that protect their investments.

Coverage TypeEstimated Cost RangeCoverage Limit
General Liability Insurance$500 – $2,000/yearMinimum $1,000,000 per occurrence- Varies by Square Footage of location and Gross Revenue
Workers’ Compensation Insurance$1,500 –Varies based on payroll
Crop Insurance$1,200 – $10,000/yearVaries based on crop value

This table highlights the importance of assessing your unique risk profile and operational scale, as larger operations involving more employees or extensive crops will likely face higher premiums.

What are the California DCC Surety Bond Requirements for Cannabis Businesses?

The California DCC establishes specific surety bond requirements to enhance accountability among cannabis operators. The primary objective is to protect consumers and ensure that businesses comply with local regulations.

Bond Amounts

The required bond amounts generally start from $5,000 per license, but locales like Coalinga require more, reflecting municipal regulations. These distinctions underscore the necessity for businesses to adequately verify their local bond amounts.

Application Process

Fulfilling the application process involves several steps, from credit checks to submitting comprehensive business documentation, which ultimately impacts the overall underwriting decision. Being well-prepared can facilitate a quicker bonding process.

Eligibility Criteria

To qualify for a surety bond, applicants generally must have a solid credit profile. However, those with lower scores can still secure bonds, albeit typically at higher premiums, reflecting their risk profile. Understanding these qualifications helps businesses plan their bonding applications effectively.

Additional Information

Overall, obtaining a DCC-required surety bond is a vital step towards achieving compliance and operating legally within California’s cannabis industry. This legal backing not only protects consumers but also supports the integrity of the cannabis market.

Why is a DCC surety bond essential for cannabis license approval?

Having a DCC surety bond is critical for cannabis license approval as it acts as a protective measure to ensure compliance with state regulations. It symbolizes a business’s commitment to adhere to legal and operational standards, offering a safeguard for consumers against potential misconduct.

How to apply for a DCC surety bond in California?

The process of applying for a DCC surety bond involves several key steps: gathering necessary documents, understanding local requirements, and engaging with bond issuers. As noted, the necessary documentation typically includes a business plan and financial statements, which provide a clear picture of the operation’s stability.

How is Cannabis Business Insurance Cost Determined in California?

The cost of cannabis business insurance is influenced by various factors, including business size, location, and the specific risks associated with the operation. Insurance providers assess these elements to tailor policies that align with the business’s specific needs and exposures.

Experts emphasize that securing adequate policies is foundational for weathering unforeseen liabilities in a complex marketplace.

Risk Management and Insurance in the Legal Cannabis Industry Insurance is a critical risk management tool used by individuals and businesses to protect against unforeseen losses, and we now turn to consider the emerging insurance market for the state-legal cannabis industry that offers products and services in a complex regulatory environment. Cannabis and Insurance, FJ Mootz III, 2019

What factors influence the cost of cannabis insurance coverage?

Several critical factors impact the cost of cannabis insurance premiums. These include:

  1. Business Size: The scale of operations directly correlates to premiums; larger businesses typically face higher costs due to increased risks.
  2. Type of Coverage Needed: Specific requirements, such as those for product liability or workers’ compensation insurance, factor heavily into overall costs.
  3. Location: Businesses in high-risk urban areas or regions with complex regulations may incur higher insurance rates.

How do different cannabis license types affect insurance premiums?

Various cannabis license types can influence insurance costs significantly. For example, cultivation licenses may incur different liabilities compared to retail licenses, thus resulting in distinct rate considerations by insurers. Consequently, it’s important for operators to understand how their specific license impacts their insurance needs.

What Types of Cannabis Insurance Coverage Are Required or Recommended in California?

California cannabis businesses must navigate a complex web of insurance products to adequately safeguard their operations. While some coverages are legally mandated, others are strongly recommended based on operational risks.

General Liability Insurance

This insurance typically provides essential coverage for user injury claims linked to products or negligence, contributing to overall risk mitigation strategies that protect the business.

Workers’ Compensation Insurance

This type of coverage is legally mandated for any business with employees and is vital for safeguarding workers against job-related injuries while also ensuring compliance with state laws.

Crop Insurance

Recommended but not mandatory, crop insurance serves to protect against losses due to adverse weather conditions, pests, or crop diseases, thereby ensuring financial sustainability.

Product Liability Insurance

As cannabis products enter an evolving market, product liability insurance becomes essential in protecting businesses from claims stemming from product defects or health issues associated with consumption.

How do cannabis-specific insurance products address unique industry risks?

Many cannabis-specific insurance products are designed to address the unique risks faced by cannabis operations. For instance, specialized coverages can provide protection against crop loss, theft, or product liability. Given the complexities of the cannabis industry, working with specialized insurance providers like So. Cals Best Insurance Services can greatly aid businesses in obtaining tailored policies that effectively reduce risk exposure.

How Can California Cannabis Businesses Ensure Compliance with 2026 Regulatory Updates?

The cannabis industry is continually evolving as regulations are revised, making it essential for businesses to stay informed about the latest compliance requirements.

What are the latest 2026 changes to DCC insurance and bonding requirements?

Businesses must remain vigilant regarding changes to insurance and bonding requirements set forth by the DCC, ensuring they adapt their policies and procedures in a timely manner to maintain operational compliance.

How can So. Cals Best Insurance Services assist with compliance and bond procurement?

Specialized providers such as So. Cals Best Insurance Services are equipped to guide cannabis businesses through complex regulatory landscapes, offering tailored insurance solutions and support in securing necessary surety bonds. For businesses operating outside California, such as those expanding into other emerging markets like cannabis insurance New York or cannabis insurance Minnesota, understanding state-specific mandates remains equally critical.

Navigating these expanding markets often presents distinct financial and operational hurdles for new enterprises.

Challenges of Obtaining Cannabis Business Insurance Coverage To add to the challenges of cannabis companies, one of the critical methods businesses have used for risk management – insurance – is expensive, difficult to obtain and, in many cases, highly restrictive regarding coverage terms for operations. Introduction to Cannabis and Insurance, 2020

Ready to Get Covered?

Don’t leave your cannabis business exposed to compliance gaps or uncovered risks. Get a quote from OG Cannabis Insurance today and secure the bonding and coverage your California operation needs.

Frequently Asked Questions

What is the standard surety bond amount required for California cannabis businesses?

The standard bond amount is $5,000 per license under DCC requirements. However, some municipalities impose higher amounts — for example, Coalinga requires bonds of up to $25,000 — so operators should confirm local requirements before applying, especially if operating in multiple jurisdictions.

What insurance coverage is required for cannabis businesses in California?

Cannabis businesses generally need General Liability Insurance (minimum $1,000,000 per occurrence, often with $2,000,000 aggregate limits) and Workers’ Compensation Insurance if they have employees, as mandated by California law. Crop Insurance and Product Liability Insurance are not always required but are strongly recommended to protect against additional operational risks.

How much does cannabis business insurance cost in California?

Costs vary based on coverage type, business size, and risk exposure. General Liability Insurance typically runs $500–$2,000 per year, Workers’ Compensation is based on payroll, and Crop Insurance ranges from $1,200–$10,000 per year depending on crop value. Larger operations with more employees or extensive crops generally face higher premiums.

How long does it take to get a surety bond for a cannabis business?

Most surety bonds are issued within 1 to 2 business days once the required documentation — including business plans, financial statements, and credit information — has been submitted, allowing businesses to move toward licensing more quickly than with traditional financing.

Is product liability insurance necessary for cannabis businesses?

While not always legally mandated, product liability insurance is increasingly important as cannabis products reach a growing market. It protects businesses from claims tied to product defects or health issues associated with consumption, making it a valuable addition to a comprehensive coverage plan.

Copyright © OG Cannabis Insurance. All Rights Reserved.

img Click To Call!